A supplier transfer coming from a personal account, collected VAT mixed with weekend purchases, a bank reconciliation that takes half a day each month: these situations are seen among leaders who are nonetheless generating several tens of thousands of euros in annual turnover. The professional account is not just a simple banking product. It is the operational foundation that structures cash flow, accelerates accounting, and clarifies the financial flows of a business.
Dedicated account or professional account: a distinction that changes costs
Confusion persists between “professional account” in the marketing sense of banks and “account dedicated to the activity” in the legal sense. For micro-entrepreneurs and sole proprietors, the law requires a dedicated account only if the turnover exceeds 10,000 euros for two consecutive calendar years. This dedicated account can be a simple current account separate from the personal account, not necessarily an account labeled “pro” by the bank.
The nuance has a direct impact on fees. A classic current account used as a dedicated account often costs zero euros per month. A professional bank account charges maintenance fees, transaction commissions, and sometimes fees per operation. For a small business that issues a few dozen invoices per month, the annual cost difference can be significant without the additional features being truly utilized.
Before subscribing, it is beneficial to list precisely what is needed: integrated payment terminal, currency collection, authorized overdraft, or simply a separate IBAN with accounting access. By comparing the available offers, especially the accounts scalora-business.fr on Génération Entreprise, one can more quickly identify the formulas suited to their actual business volume.
Professional banking fees: what the 2026 simplification law changes concretely
Law No. 2026-403 of May 26, 2026, known as the economic life simplification law, brings two concrete changes for leaders of small and medium-sized enterprises (SMEs).
- The closure of any business deposit account or savings account is now free of charge. No fees can be charged for closing the account. Changing professional banks no longer incurs exit costs, which reduces the lock-in effect that some institutions exploited.
- Banks must provide a free annual summary statement of banking fees to microenterprises. This standardized document facilitates comparisons between institutions and highlights “invisible” fees (transaction commissions, maintenance fees, cost per SEPA transfer).
- These two combined measures enhance the banking mobility of small structures. One can now test a professional neobank for a few months and then return to a traditional bank without closure penalties.
In practice, this annual statement is a management tool. It is compared with the actual volume of operations to check if the subscribed package corresponds to usage. Many leaders pay for a “premium” package while their activity generates only a few weekly transfers.
Accounting automation and pro account: the real productivity lever
The separation of flows is just the first step. The operational gain lies in the connection between the professional account and management tools. When the pro account is synchronized with accounting software, each transaction is automatically categorized. Bank reconciliation, which used to take several hours a month manually, is reduced to a few minutes of verification.
Several professional neobanks directly integrate electronic invoicing into their interface. This convergence becomes strategic with the gradual generalization of electronic invoicing in France. A pro account connected to an invoicing tool reduces double entries and posting errors.
Responses vary on this point depending on the size of the business. For a freelancer who issues fewer than ten invoices per month, the native synchronization of a neobank is often sufficient. For an SME with dozens of suppliers and daily collections, dedicated accounting software (connected to the bank flow via API) remains more reliable than an all-in-one solution.
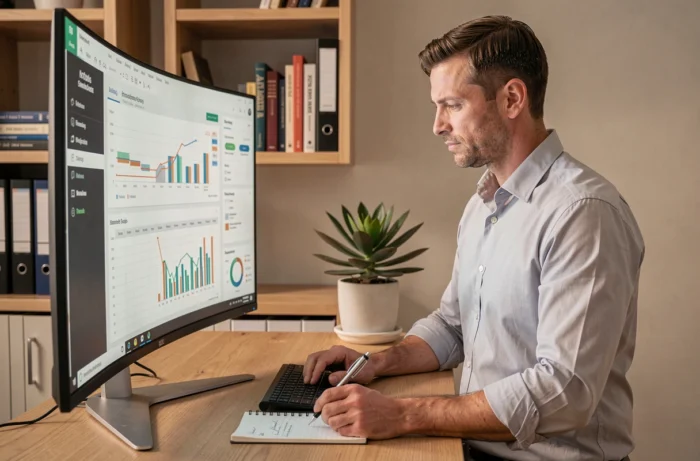
Cash flow dashboard: building a reliable vision from the pro account
A well-configured professional account feeds directly into a cash flow dashboard. The goal is not to produce sophisticated reporting but to answer a simple question: in how many weeks will the available cash flow fall below the critical threshold?
To build this dashboard, one starts from three data points extracted from the pro account:
- The actual balance to date, minus issued checks not yet debited and scheduled withdrawals.
- Projected collections: invoices issued with their due date, historical payment delays by client.
- Recurring disbursements: rent, social charges, tax deadlines (VAT, corporate tax or personal income tax), loan repayments.
The projected balance in four weeks is the most useful management indicator for a small business. It allows anticipating a cash flow need before it becomes an unplanned overdraft and to postpone an investment or follow up with a client who is late on payment.
Some pro accounts offer this projection directly in the banking app. When this is not the case, a simple spreadsheet connected to the CSV export of the account does the job, provided it is updated weekly.
Criteria for choosing a pro account suited to actual activity
The best professional account is not the one that displays the most features, but the one that matches the volume and nature of the company’s operations. A craftsman who primarily collects by credit card needs an integrated terminal with competitive commissions. A consultant who invoices three clients per month only needs a dedicated IBAN and a clean accounting export.
Checking the actual cost per operation rather than the monthly subscription price helps avoid unpleasant surprises. A package costing a few euros per month becomes expensive if each outgoing transfer is charged extra. Conversely, a higher subscription with unlimited transfers can prove cost-effective from around twenty monthly operations.
The portability facilitated by the 2026 law changes the game: one is no longer committed long-term. Testing an account for a quarter, measuring its actual fees using the standardized annual statement, and then making a decision is now a process without friction or exit costs. The pro account becomes a management tool that one adjusts, not a contract that one endures.